This article first appeared in The Edge Malaysia Weekly on September 8, 2025 – September 14, 2025
TUCKED away on the seventh floor of the ageing Wisma Equity — directly across from the gleaming Petronas Twin Towers — is the Malaysian office of London-listed Anglo Eastern Plantations plc (AEP).
The plantation company maintains a relatively modest presence in Malaysia, operating just a 3,414ha estate in Cenderung, Terengganu, through Anglo-Eastern Plantations (M) Sdn Bhd. In contrast, its operations in Indonesia are far more extensive, comprising seven estates in North Sumatera, two each in Bengkulu and Kalimantan, and one each in Bangka and Riau—covering a total of 65,686ha.
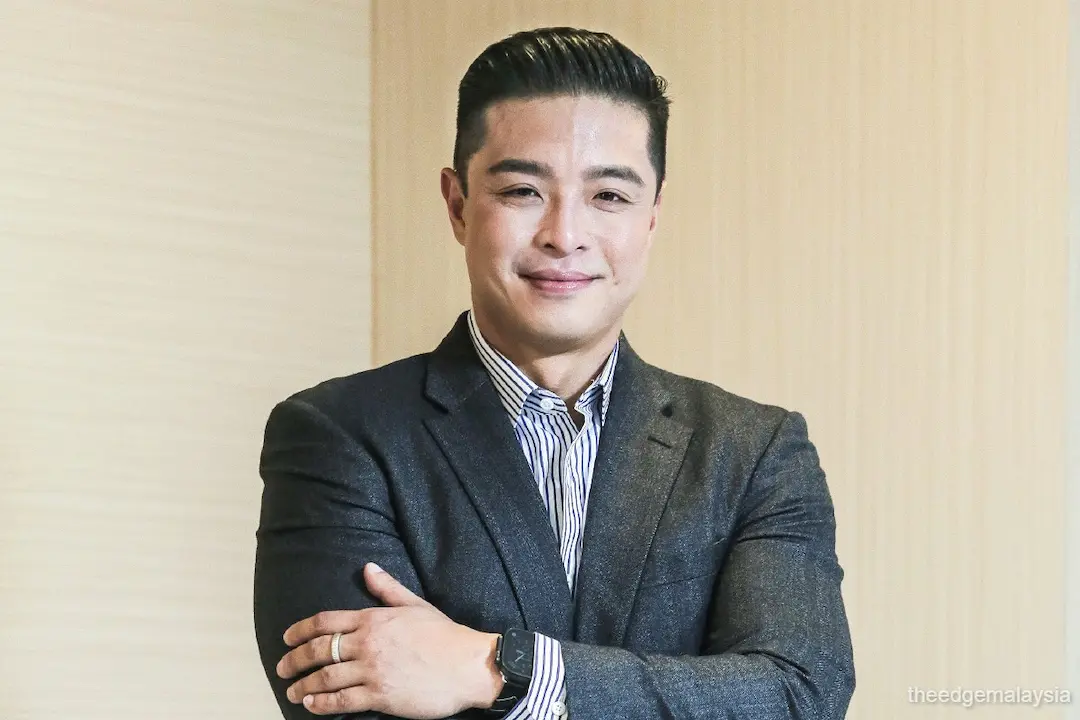
AEP executive director Marcus Chan Jau Chwen reminisces, “[AEP] was listed in London in 1985. When they took over, there were four mixed-crop plantations, one palm oil mill … and my late father was quite aggressive in expansion. We’re now sitting on 14 estates and seven mills [and] growing. He was really interested in this [business]; that’s why he built this. This [plantation business] was a passion of his,” Marcus, 40, tells says The Edge in an exclusive interview.
“I grew up coming to this building; it was a racecourse then,” he adds, referring to the KLCC site across from Wisma Equity.
By “they”, Chan is referring to his late parents: Dick Chan Teik Huat, a chartered accountant formerly with Kassim Chan & Co — which later became Deloitte Kassim Chan — who passed away in 2019; and Lim Siew Kim, who died in July 2022. She was the daughter of the late Genting Group patriarch, Tan Sri Lim Goh Tong, who remains highly revered nearly 18 years after his passing in October 2007.
Dick and Siew Kim met in 1968 when he was auditing the financials of Goh Tong’s flagship company, Genting. Siew Kim was involved in running the group’s hotels.
Together, they owned several businesses, including Metroplex Bhd, which built Wisma Equity and Wisma Central, also in the KLCC vicinity, among other developments. Siew Kim also controlled a substantial stake in stockbroking outfit Apex Equity Holdings Bhd (KL:APEX) with Dick’s younger brother, veteran stockbroker Chan Guan Seng, who founded the company.
AEP came under the control of Dick and Siew Kim in November 1993, when their vehicle, Genton International Ltd, acquired a controlling stake in the company. The previous majority shareholder, a British firm, was looking to divest because of financial difficulties.
Marcus says of his corporate pedigree: “Obviously, I’m proud of the legacy and what they left behind. But I see it (as maintaining) the values that they left behind (rather than anything else) being a pressure point. Of course, there are the expectations that come with that lineage but, choosing to take it in stride, I focus on moving forward, contributing my own [bit to the legacy].”

Besides Dick, Marcus’ predecessors at AEP were quite well-known corporate figures. Patrick Low Han Hing (now Johari Low Abdullah), who is now with Rockwills and was with Arab-Malaysian Merchant Bank, was appointed deputy president and CEO of AEP on Sept 12, 1994, strengthening Genton’s grip on its new asset.
Then, from 2008 to end-2024, Datuk John Lim Ewe Chuan, a former auditor, helmed AEP and played a significant role in the company’s development over the years. Another known corporate personality, Lim Tian Huat, formerly of Arthur Andersen & Co, was an advisor at AEP.
In the initial years following the acquisition, AEP experienced a period of consolidation as Dick, Siew Kim and the management team acclimatised to overseeing plantation operations. Strategic expansion began in 1995 with a one-for-two rights issue to support growth initiatives, including the acquisition of the 800ha Anak Tasik estate in North Sumatra. That year, AEP also secured 17,600ha in Bengkulu, southern Sumatra, along with a young oil palm estate in Peninsular Malaysia. In line with its development strategy, the company commissioned a 40 metric tonne per hour (mt/hr) mill in Bengkulu in 2002, which was subsequently upgraded to 60mt/hr in 2004.
For many years, the company maintained a low profile and attracted little public attention — until recently. Even then, the interest has largely revolved around a legal dispute in which Siew Kim’s two daughters, Chan T’shiao Li and Kimberly Chan T’shiao Miin, have alleged fraud in the execution of her will, a matter currently before the courts.
Marcus downplays the impact of the dispute, saying: “No, [the dispute] doesn’t affect AEP. My accountability is to the shareholders, and the company’s operations remain unaffected.”
Gaining traction
In mid-April this year, AEP’s stock started to stir and had gained close to 75% by August, surpassing the 1,000 pence mark for the first time in its history and hitting a record high of 1,265 pence on Aug 27.
The jump in its share price was attributed to its financial results. For the six months ended June, AEP managed to chalk up after-tax profits of US$48.8 million (RM206.45 million), a 75% year-on-year gain and buoyed by a rise in selling prices as well as higher sales volumes. Revenue in the period was up 39% to US$230.5 million.
In its financial results announcement, AEP says its average crude palm oil (CPO) ex-mill price for the first six months was up 15% y-o-y at US$863 per tonne, from US$749 per tonne. Palm kernel prices averaged at US$738 per tonne, up 80% y-o-y, from US$411 per tonne.
AEP’s balance sheet looks strong, with zero borrowings as at June 30, 2025, and a substantial cash position. As at end-June, the company held US$244.7 million in cash and cash equivalents, including short-term bank deposits — up from US$183.2 million at end-2024 and US$150.8 million a year earlier. The increase primarily reflects cash generated from operations of US$67.6 million, partially offset by capital expenditure of US$11.2 million and a foreign exchange gain of US$300,000.
Its net assets for the period in review were pegged at US$584.8 million, up from US$558.5 million at end-2024 and US$510.3 million at end-June 2025. The US$26.3 million increase since end-2024 was a result of a six-month profit of US$48.8 million, partially offset by a dividend declaration of US$20.1 million.
Marcus says, “I believe that [the better earnings are] sustainable. You know palm oil; the long-term fundamentals are compelling even though there’s price volatility. It’s a commodity that will always have some sort of demand.
“There are many reasons [for the better financials] but, obviously, there are favourable market conditions for CPO price. [As to] kernel price, we have done some implementation for better crops, for the mills especially.”
Expansion plans
AEP’s land bank stands at roughly 69,000ha — larger than TH Plantations Bhd’s (KL:THPLANT) 56,000ha, but considerably smaller than that of FGV Holdings Bhd, which manages 438,867ha across Malaysia and Indonesia.
On the possibility of expansion, Marcus says: “Obviously, there’s always the magic number of 100,000ha, but it’s not really our focus. We’d rather grow with strategy involved. [But] we’re not shutting any doors; when it comes to expansion, we are always looking but it’s more about the quality of the estate.
“We’re not going to just rush out there and just keep buying just because we have the money … There are [ongoing talks to buy plantations] but it always comes down to the quality of the plantation and whether it falls in line with RSPO (Roundtable on Sustainable Palm Oil) standards, because if we come up with plantations that don’t comply, it’s trouble for us in the future when we ultimately want to get certification.”
Regarding the location of potential expansion, Marcus says: “We’re not going to constrain ourselves geographically. [But] we are looking at East Malaysia … If a good offer comes along after our due diligence and we find that it is quality and fits into our requirements [we will buy it].
“We are active/aggressive. If I [just] say aggressive, then it’s sort of like we’ll just pay whatever for whatever [assets]. We want to be more prudent about our expansion strategy.
“Sometimes, the issues are size … We can’t look at offers below a certain [baseline, say,] 5,000ha. The philosophy is this: If the targeted plantation is small but it’s near our existing plantations, we’ll take it. But if it’s a new area, if it’s too small, [it would not make sense] for us to build a new team.
“But if the targeted plantations are near us, and we have our systems in place, however small, we would likely take it … Definitely, we [focus on areas] surrounding our current operations so that the cost of expansion is not as high.”
He adds that the company is also investing in efficiency improvements, including the use of technology to boost yields — such as implementing enhanced enterprise resource planning (ERP) systems to improve reporting accuracy and optimise fertilisation, among other areas.
Other issues
The average age of AEP’s oil palms is 14 years, with 39% in the prime category; 25%, young; 12%, immature; and 24%, old.
As for its replanting programme, Marcus says: “We are targeting replanting about 10,000ha in the next four years, in cycles … We identify the blocks within the plantations and then start with the seedlings. And then there is a programme in place so that there’s not too much operational disruption.”
AEP’s fresh fruit bunch yield stood at 17.8 tonnes per ha in 2024, down from 19.4 tonnes per ha in 2023. Its oil extraction rate (OER) in 2024 stood at 20.2% compared to 20.8% in 2023, according to its 2024 annual report.
AEP’s oil yield was 17.8 tonnes per ha in 2024, compared to 19.4 tonnes per ha in 2023.
“We’d like to improve, obviously. We’d like to sit at 20% to 23%. A factor that affects the OER is external crops. [The breakdown is] roughly 50:50 because our plantation profile is that we don’t have big plantations; the outside crops are the ones that drag [the percentage down].
“Our personal harvest, our crop, is we … high quality. So, you can’t split our personal crop, but you could say 20% to 23%.”
AEP is trading at multiples of 7 to 7.5 times on the London Stock Exchange. In stark contrast, MKH Oil Palm (East Kalimantan) Bhd’s (KL:MKHOP) IPO in March 2024 — comprising a public issuance of 220 million shares, representing 21.5% of its enlarged share capital, along with an offer for sale of 30.7 million existing shares, representing 3% of the enlarged share capital — was priced at 62 sen, valuing it at more than 20 times its FY2023 earnings of RM30.4 million.
Asked whether there were plans for a dual listing or similar corporate exercise, Marcus says such a move is “not in the current plans”.